Federal Government of Nigeria Introduces Expatriate Employment Levy
March 4, 2024
Summary
On 27 February 2024, the Federal Government of Nigeria (FGN) introduced the Expatriate Employment Levy (EEL) – a mandatory financial contribution imposed on employers who hire expatriate workers in Nigeria. Some of the objectives of the EEL are to promote skill transfer and knowledge sharing, balance economic growth and social welfare, enhance collaboration between public and private sectors and address demographic shifts. The EEL which is to be administered by the Nigeria Immigration Service (NIS) will be implemented from 15 March 2024. The NIS has communicated that the last date of compliance for the EEL is 15 April 2024.
Details
The EEL is intended to be a fiscal measure designed to address certain socio-economic considerations in the country and it seeks to balance the benefits of expatriate employment with the protection of Nigeria’s local labour markets and resources. The initiative aims to narrow the wage disparities between expatriates and Nigerian employees. As stated, The key objectives of the EEL include promoting skill transfer and knowledge exchange, ensuring a balance between economic advancement and social well-being, strengthening collaboration between the public and private sectors, and addressing demographic changes.
The following are important points to note about the EEL:
a. The EEL is a mandatory levy imposed by the Federal Government on employers across diverse sectors in Nigeria, for hiring expatriate workers and is payable via an online portal online portal – www.eel.interior.gov.ng.
b. The EEL is fixed at 15,000 USD for directors and 10,000 USD for other categories of expatriates. It is payable annually.
c. The EEL is obligatory and payable by companies in Nigeria that engage expatriates in their workforce. The relevant companies encompass businesses of varying sizes in Nigeria, including private sector industries, multinational corporations, small and medium-sized enterprises (SMEs).
d. The EEL is payable for non-citizen expatriate workers employed in Nigeria. This includes individuals holding certain types of work permits, visas, or other temporary residency arrangements, who work in Nigeria for 183 days or more within a fiscal year. In the case of expatriates with short-term employments, they shall be required to pay the EEL if they have spent an aggregate of 183 days or more within a fiscal year.
e. The EEL does not apply to accredited staff of diplomatic missions, government officials and other organisations/persons stated in the Nigeria Immigration Service approved exemption list.
f. Employers of expatriates are required and are responsible for maintaining accurate records, submitting timely reports and adhering to reporting deadlines, while the expatriates are required to ensure that accurate information is provided to the employer.
Penalty/Sanctions
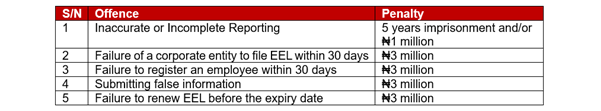
Organisations with expatriate employees are to take note of the compliance obligations detailed above to avoid applicable penalties for default. We have detailed below the penalties for non – compliance.
Implication
The introduction of the EEL has been met with varying concerns by stakeholders, particularly with respect to how it may impact corporates and sectors that require skills not readily resident. It is therefore important for companies to evaluate the potential impact of the EEL on their business and take necessary steps to comply in order to avoid penalties.
In addition, as the FGN continues to take steps towards improving the ease of doing business in Nigeria, it should put in place appropriate mechanisms to track the benefits of the EEL vis-a-vis any unintended consequences as the EEL has the potential of increasing the cost of doing business and places additional compliance burden on businesses.
Andersen will continue to monitor this space and provide relevant updates.